Executive summary
Population growth has long been one of the clearest indicators of market momentum. But population totals alone don’t explain why markets grow or how demand changes. CENSAI ranked markets by net migration from Q4 2025 through Q1 2026 and selected five CBSAs that stood out for distinct reasons beyond population growth. The result: five different stories from Idaho’s capital city to Florida’s most popular retirement community.
Five growth markets and the data defining them
Domestic migration volume has declined since 2021. In the first half of 2025, total mover volume was the lowest observed in eight years.
Population:
3.9M
Median income:
$81K
Net migration
(Q4 2025-Q1 2026):
+2,364
Migration cooling, but not freezing
Long defined by growth, Phoenix’s migration cycle took notable turns during the last six years. The market reached two pandemic-era peaks, adding nearly 18,000 net new residents in 2020 and more than 17,000 in 2021. After 2022, migration declined sharply, reaching just +656 in Q1 2026 — the lowest first-quarter total in the eight-year dataset. The current outlook points toward a gradual recovery.
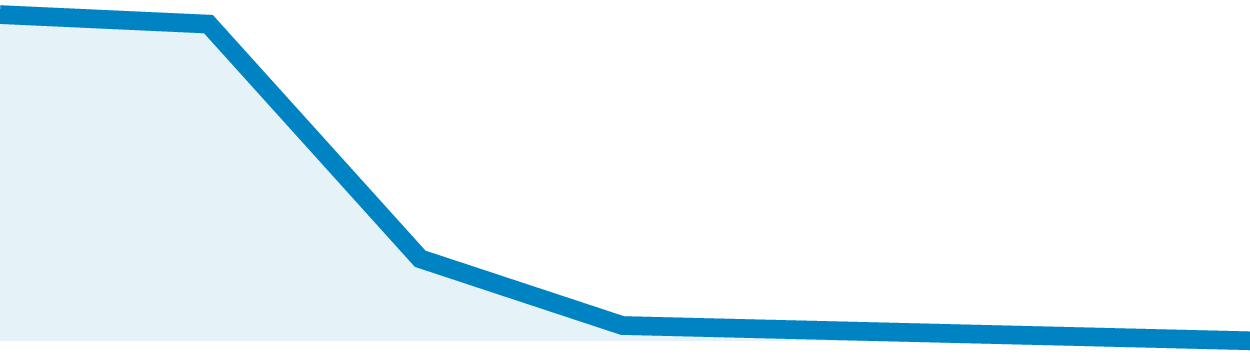
Growth trajectory (2020-2026)
Moving upmarket
Over the past year, Phoenix posted the strongest income shift of any market in this report. The share of residents earning under $50K declined by 3 percentage points; $100K+ increased by 6.4. These numbers continue a broader eight-year trend: Since 2018, the under-$50K population share has nearly halved, while the $100K+ segment has about doubled. Phoenix now ranks among the top 11% nationally for high-income households.
|
Under $50K:  3 pts |
$100K+:  6.4 pts |
|
National ranking: Top 11% |
|
The young boomtown begins to age
Phoenix’s demographic story has historically been tied to younger households. From 2018 onward, residents ages 30–45 gained the most share, reinforcing the market’s reputation as a destination for working-age growth. Meanwhile, residents ages 65+ (the largest age group at 32%) remained relatively stable. The latest year marked a shift. Residents ages 65 and older became the fastest-growing age group, increasing by 1 percentage point. Phoenix is still attracting working-age households, but older residents are an increasingly important part of the demand picture.
Changing feeder markets
Phoenix’s traditional growth story has been tied to California. Today, its strongest feeder markets are moving toward Arizona and the Pacific Northwest, with Spokane appearing as a new source of migration.
Affordability and investment signals
Phoenix remains challenging for buyers, but rental affordability creates a different opportunity profile.
- Investability score: 48
- Mortgage affordability score: 41
- Rental affordability: top 28% nationally
What it means
Phoenix is no longer just a population-growth story. The market’s next phase may be defined by a combination of higher-income households, changing migration sources, and an evolving age profile. While migration momentum has cooled from its pandemic peak, the underlying demand suggests a market undergoing transformation. For organizations evaluating Phoenix, understanding who is driving growth may be the more important question than how much growth is occurring.
2. Dallas-Fort Worth-Arlington, TX: Big market, unconventional migration
Population:
6.6M
Median income:
$82K
Net migration
(Q4 2025-Q1 2026):
+1,979
Fewer domestic movers
Dallas-Fort Worth remains one of the country’s largest growth markets. Migration is the primary driver, just not the domestic kind. Of the 1.5 million residents DFW added over the past several years, only 39,000 came from domestic movers. The rest didn’t arrive from other U.S. metros, and that’s an important nuance when trying to understand changing audiences and emerging opportunities in major markets.
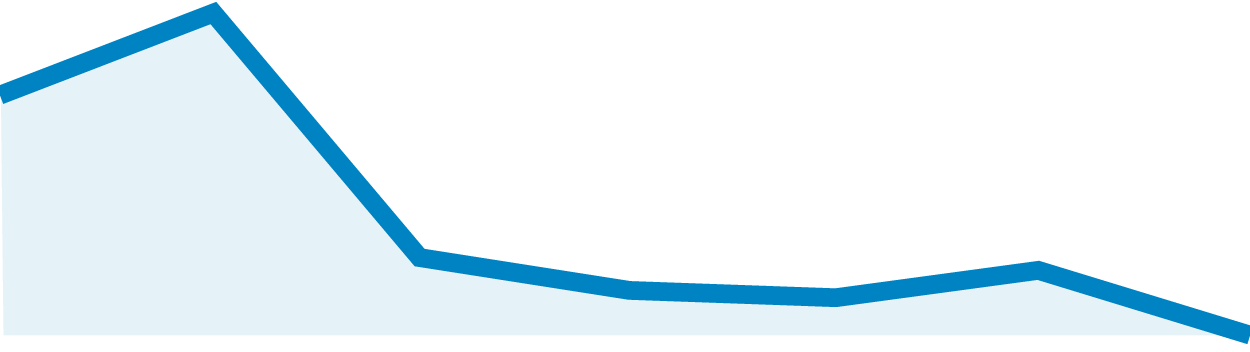
Growth trajectory (2020-2026)
Income dip and recovery
Dallas-Fort Worth drifted upmarket through the pandemic years, then went flat in 2023–2024. The share of households earning $100K+ shrank for a year before recovering, the only market in this report where that happened. The latest trend shows a mild improvement, but nothing close to the pandemic pace. The under-$50K share declined 0.9 points, while the $100K+ share increased 0.7 points.
|
Lower-income share |
|
Higher-income share |
Demographics shifting older fast
This year, 65+ grew faster than any other bracket, a reversal from the market’s historic trend where 18-30 led growth. Despite showing almost no net migration, DFW is nonetheless skewing slightly older.
Texas-to-Texas feeder markets
DFW’s migration sources have remained remarkably consistent. Houston, Austin, and San Antonio have been the dominant feeder markets for eight years, reinforcing DFW’s role as a regional growth center rather than a national relocation destination.
Affordability and investment signals
DFW presents one of the more challenging combinations among the five markets. Its size and population growth are significant strengths, but the data suggests a more complicated demand picture than a “high-growth” label implies. DFW scores 28/100 on CENSAI’s investability index — bottom 10% nationally — which likely reflects overbuilding.
What it means
A market can continue expanding without being driven by large-scale migration, and that distinction matters. Understanding whether growth comes from relocation, household formation, income shifts, or demographic change provides a clearer view of future demand. For DFW, the key question may not be whether the market will continue growing, but whether growth is translating into demand that supports future opportunities.
3. Myrtle Beach-Conway-North Myrtle Beach, SC-NC: Momentum that never stopped
Population:
595K
Median income:
$55K
Net migration
(Q4 2025-Q1 2026):
+3,814
Migration that kept moving
Myrtle Beach not only resisted the migration swings shown in other markets, but also recorded steady momentum and posted the largest absolute gain of any CBSA in the country this quarter. The forecast remains positive, with expected growth of 2.31%.
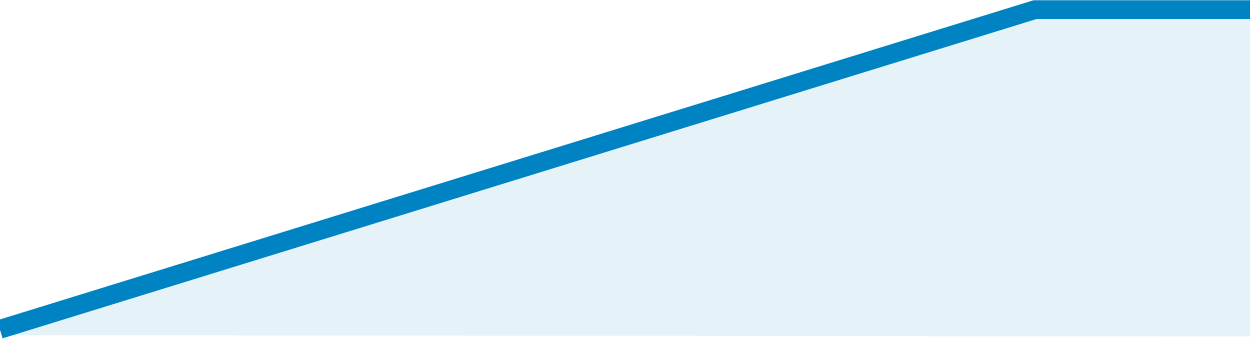
Growth trajectory (2020-2026)
The income growth winner
Since 2018, the under-$25K share has declined from 32% to 15%. Myrtle Beach just posted its fastest single-year income move in the market’s eight-year history: under-$50K down 3.6 points, $100K+ up 1.4. Of all the markets in this report, Myrtle Beach carries the lowest raw median income at $55,000, but it lands in the top 37% nationally on income growth.
|
Under $50K:
3.6 pts
|
$100K+:
1.4 pts
|
|
National ranking: Top 37% |
|
Emerging retirement identity
Myrtle Beach’s 65+ share is still climbing after eight years, increasing from 35% to 41%. Unlike Phoenix, Boise, and The Villages — where recent age trends show a change or reversal — Myrtle Beach is holding to an existing pattern. Retirement identities don’t happen overnight, but data shows them taking shape.
Stable sources of demand
New residents continue to come primarily from New York, Charlotte, and Wilmington. Those sources have remained largely unchanged for years. Myrtle Beach’s migration pipeline has remained stable compared to its peers, which are experiencing a shift in where residents originate.
Affordability and investment signals
Myrtle Beach presents an interesting demand profile of a growing retiree population, stable migration sources, and improving income trends. The data suggests potential demand across multiple housing segments, including rental and age-oriented products.
What it means
Myrtle Beach’s story is one of consistent versus explosive growth. While other markets experienced sharp cycles, Myrtle Beach gradually strengthened its income profile and continued attracting an older population. The question now is how demand will continue to evolve as the market’s demographic identity becomes more established.
4. The Villages, FL: Challenging assumptions about retirement markets
Population:
157K
Median income:
$83K
Net migration
(Q4 2025-Q1 2026):
+1,759
Steady market, changing pace
The Villages’ migration story is marked by two pandemic peaks before a slowdown in Q1 2026. Even so, its projected of 3.47% is the strongest of the five markets in this report.
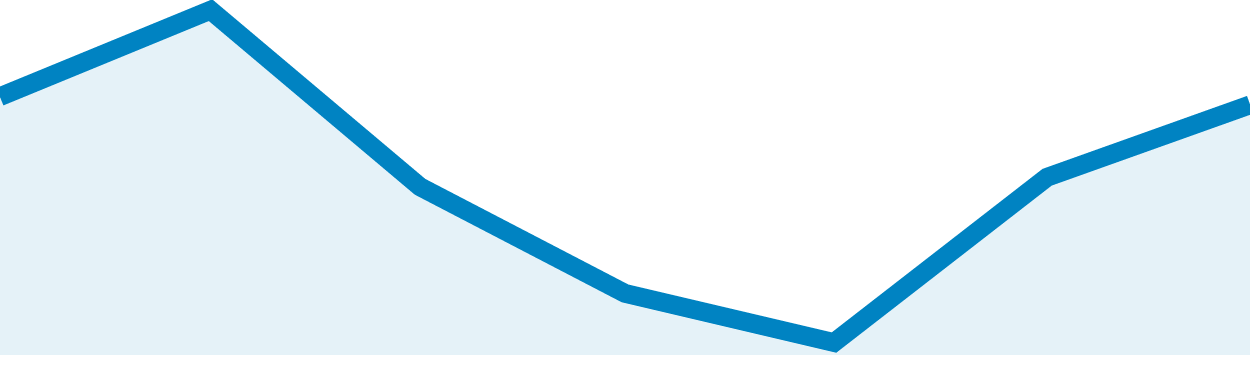
Growth trajectory (2020-2026)
The most consistent income climb
Since 2018, the under-$50K share has roughly halved. The $100K+ share has continued increasing gradually. Unlike Phoenix and Myrtle Beach, where income growth accelerated sharply, The Villages has followed a steadier path with no major recent acceleration. The Villages carries the highest median income in the group at $84,000.
|
Under $50K:
0.9 pts
|
$100K+:
1.2 pts
|
|
National ranking: Top 10% |
|
A retirement market looking less retired
Residents 65+ have represented roughly 64%–65% of The Villages’ population for eight years, but the latest year brought unexpected changes. The 65+ share declined by 0.7 percentage points, which is notable when it occurs in the nation’s most retirement-defined market. And the 30–45 age group grew faster than any other segment.
Increasingly localized feeder markets
The Villages’ feeder markets have consolidated over time. Historically, the market attracted residents from states such as New York, Chicago, and Detroit. Today, migration is increasingly driven by in-state Florida moves.
Affordability and investment signals
The Villages is among the strongest markets in this group in terms of investability and mortgage affordability, trailing only Boise. Rental affordability is the challenge. Despite relatively inexpensive rents, The Villages ranks near the bottom nationally, suggesting a potential mismatch between available rental options and tenant demand.
What it means
Even highly specialized markets continue to evolve. The latest demographic data shows that market identities are never immovable. Small shifts in age, income, and migration patterns can reveal changing demand dynamics in places with a well-established reputation, such as The Villages.
5. Boise City, ID: Same boom, different age group
Population:
656K
Median income:
$78K
Net migration
(Q4 2025-Q1 2026):
+1,822
Strong growth in spite of setbacks
No market in this report swung harder than Boise. Migration spiked to +5,533 in 2021, crashed to near-zero in 2022, partially rebounded from 2023 to 2025, and is cooling again this quarter at +440. The current forecast remains positive at +1.37%, and though that’s one of the weaker signals in this report, Idaho still ranks among the strongest and fastest-growing U.S. markets.
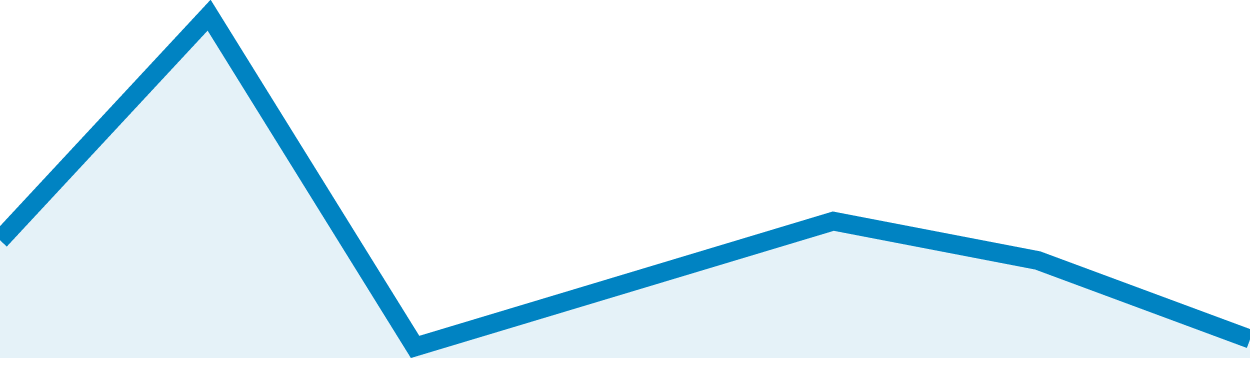
Growth trajectory (2020-2026)
A dramatic upmarket shift
The income story is the sharpest upmarket shift in the group. Since 2018, the under-$25K population share declined from 16% to 5%. The $200K+ population share more than doubled. Income growth tracked closely with migration patterns, accelerating during the pandemic migration surge, pausing in 2023–2024, and accelerating again with renewed migration in 2024–2025. This year, income is roughly half last year’s pace, right in step with the Q1 2026 migration cooldown.
Demographics: The biggest twist
Boise built its reputation as a young, remote-worker boomtown, but the latest data suggests an evolving identity. The 18–30 population share that peaked in 2021 has declined every year since. Meanwhile, residents ages 65+ are the fastest-growing group. Boise’s growth profile raises the question: Could this market be headed toward a retirement destination?
|
Ages 18-30 |
|
Ages 65+ |
Regional growth sources gain importance
Boise’s changing migration pattern mirrors Phoenix. Traditional California sources are fading, while regional sources are becoming more important.
Affordability and investment signals
The demand signals have always been there. The key is understanding how they’re changing as Boise moves beyond its pandemic-era boomtown identity. This market stands out on several investment-related measures.
- Highest investability score among the five markets: 74
- Top 4% nationally
- Widest buy-versus-rent affordability gap in the group
What it means
Reputation alone is not enough to drive an investment decision. A city known for attracting young remote workers is showing signs of a broader demographic transition. Income growth remains strong, investment indicators remain favorable, and migration continues. But the composition of that growth is changing. The most valuable market insights often emerge when current data challenges yesterday’s assumptions.
Final takeaways
Five markets, five changing growth stories
Population growth has always been an important market indicator. But the analysis of these five CBSAs shows why growth cannot be understood through a single metric. Migration, income, demographics, feeder markets, and affordability each reveal a different part of the story. Across the five markets, several patterns emerged.
Growth is becoming more complex
Four of the five markets experienced a boom-then-cool migration cycle following the pandemic. Myrtle Beach was the exception, maintaining steady momentum throughout the period. Overall, recent growth patterns are not moving in one direction. Some markets are recovering. Some are stabilizing. Some are changing character.
Income trends are diverging
Understanding whether a market is becoming wealthier can reveal opportunities and challenges behind population numbers. Every market in this report experienced a pause in income growth during 2023–2024, but the paths began to separate afterward.
- Phoenix and Myrtle Beach accelerated sharply.
- The Villages saw a modest improvement.
- Dallas-Fort Worth briefly dipped, then recovered.
- Boise slowed after a period of renewed momentum.
Migration sources are shifting
Where movers come from can be just as important as how many arrive. Several markets are seeing changes in where new residents originate. Phoenix, The Villages, and Boise all show a movement away from traditional feeder markets (California and Northeast) toward more regional and in-state migration patterns.
65+ are driving population movement
Market labels can hide important changes beneath the surface. The most unexpected pattern appeared in demographics. Phoenix, Dallas-Fort Worth, Myrtle Beach, and Boise — none of them traditional retirement markets — all saw residents ages 65+ become the fastest-growing age group over the past year. The Villages, the market most associated with retirement, was the only one where the 65+ population share declined.
The most actionable insights come from data that answers granular questions
- Is a growth market still growing for the same reasons it did five years ago?
- Are new residents arriving from the same places?
- Are household incomes moving up or down?
- Are demographic shifts creating new demand patterns?
The CENSAI platform answers these questions by combining population intelligence, migration analysis, demographic trends, and market-level insights to reveal who movers are and how they’re changing markets. Sign up for a free 7-day trial and explore your target market through our lens.